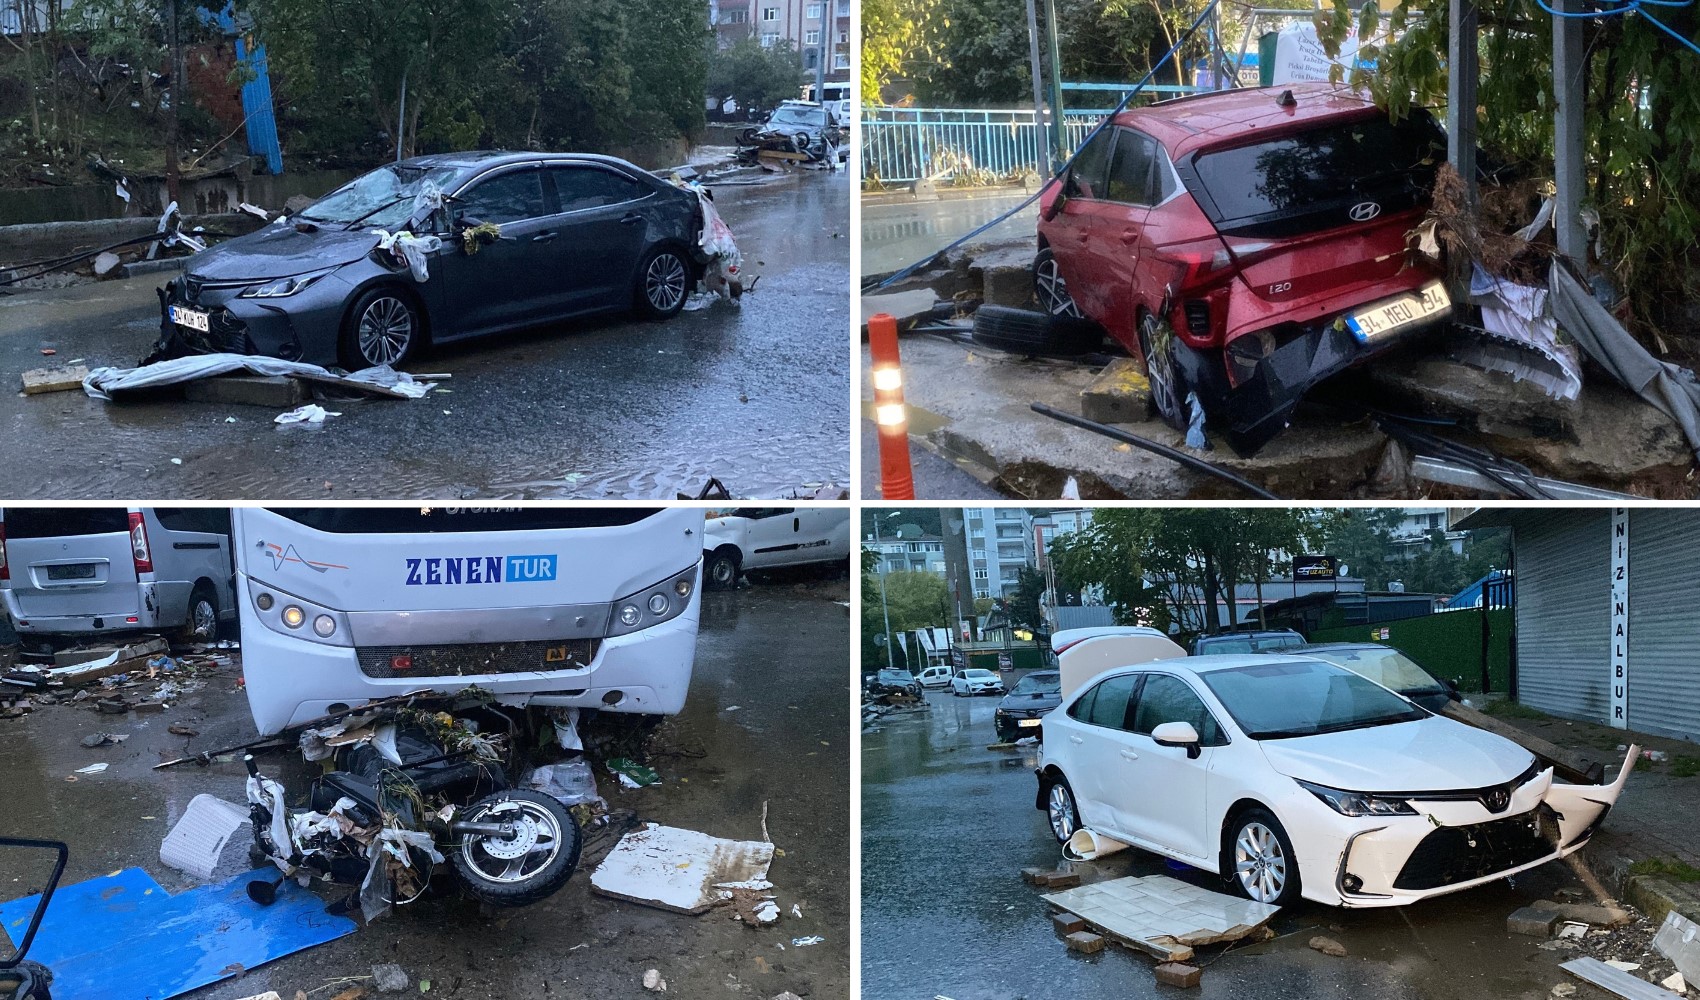
Following heavy rainfall and flooding in various regions of Turkey, questions regarding the insurance processes for those whose vehicles were damaged have increased. The Insurance Association of Turkey (TSB) has provided assessments on which policies are activated for damage caused by floods and inundation, what can be done if the notification period is missed, and whether coverage can be added later.
Under normal circumstances, damage must be reported to the insurance company within 5 business days for comprehensive insurance (kasko). However, according to information shared by the TSB, exceeding this period does not automatically eliminate the insured's right to compensation. The insurance company examines why the notification was made late and whether the delay increased the damage.
If it is determined that the damage worsened due to the delay, a reduction may be applied to the compensation to be paid, taking into account the fault of the insured. For this reason, it is important for owners of damaged vehicles to contact the insurance company as soon as possible, document the damage with photos and videos, and keep any official reports if available.
WHICH POLICY COVERS WHAT?
Compulsory traffic insurance does not cover damage caused by floods or inundation to the vehicle itself. This insurance provides coverage for damages caused to third parties due to the operation of the vehicle for which the vehicle owner is legally responsible. In cases such as a vehicle being swept away in a flood and damaging other vehicles, the circumstances of the event and the fault of the vehicle owner are evaluated separately.
For flood damage to be covered for the vehicle, the comprehensive insurance (kasko) policy must include flood and inundation coverage. If this coverage is not in the policy, additional coverage can be requested from the insurance company; however, companies are not obligated to accept this request. Furthermore, coverage added after the damage has occurred does not cover previously formed and known losses. If accepted, the new coverage becomes valid for events occurring after the date it goes into effect.
For residences, it is noted that the Compulsory Earthquake Insurance (DASK) does not cover damage caused by floods and inundation. DASK covers risks such as earthquakes and fire, explosion, tsunami, and landslides directly caused by an earthquake. For residential damage that may occur due to flooding, home insurance containing flood coverage is required.
If the insurance company rejects the damage claim, the beneficiaries can use legal channels. If it is decided during the examination that compensation should be paid, a request for interest may also be brought to the agenda depending on the conditions.
The losses of vehicle owners who do not have comprehensive insurance or whose policy does not include flood coverage are not covered by insurance in this context. However, if it is believed that third parties are at fault in the occurrence of the damage, legal action can be taken against those responsible.
News Source: 12punto